








Can you trade crypto futures in Singapore now?
There is a real crypto-derivatives offering to investigate in Singapore, but the public OKX documents do not give every retail reader the same answer. Its Singapore landing page advertises derivatives for users who pass its assessment. Its Financial terms, last updated 22 April 2026, still require accredited-investor status and an express opt-in under section 2.5.
For an accredited investor whose account is approved, OKX is our featured exchange option. For an ordinary retail reader, the sensible next step is to obtain confirmation of the eligibility terms actually attached to the account before funding derivatives. A marketing page alone does not resolve the conflicting contractual condition.
This is not a claim that Singapore bans all crypto trading, nor that every resident can immediately open a 50x position. The distinction is practical: one reader can compare an approved derivatives account today; another still needs a clear answer from the provider before the comparison becomes actionable.
| Product | What is established | Who should consider it |
|---|---|---|
| OKX Financial derivatives | A separate, unregulated derivatives service; public eligibility wording conflicts | Approved eligible users, with the applicable account terms confirmed |
| SGX crypto perpetual futures | Exchange-traded crypto contracts with restricted Singapore customer categories | Accredited, expert or institutional investors meeting the relevant access requirements |
| Local spot accounts | Buying and selling supported coins through the relevant local service | Readers who want the asset itself rather than a leveraged long or short |
| An offshore or DEX interface | Technical access alone does not establish suitable Singapore product permission | Not a substitute for the eligibility checks above |
The catalogue below retains provider-access records. It is broader than this editorial shortlist and should not be read as a list of MAS-approved retail futures accounts. In particular, a platform offering spot services locally does not automatically offer its overseas derivatives catalogue to the same customer.
Why the same OKX app can involve different companies
OKX Singapore’s payment-services permission and OKX Financial’s derivatives service are different. The Singapore terms identify the locally licensed service; the derivatives material identifies a separate provider and says that provider is not regulated. This matters even if both products appear under a familiar brand or within a connected user journey.
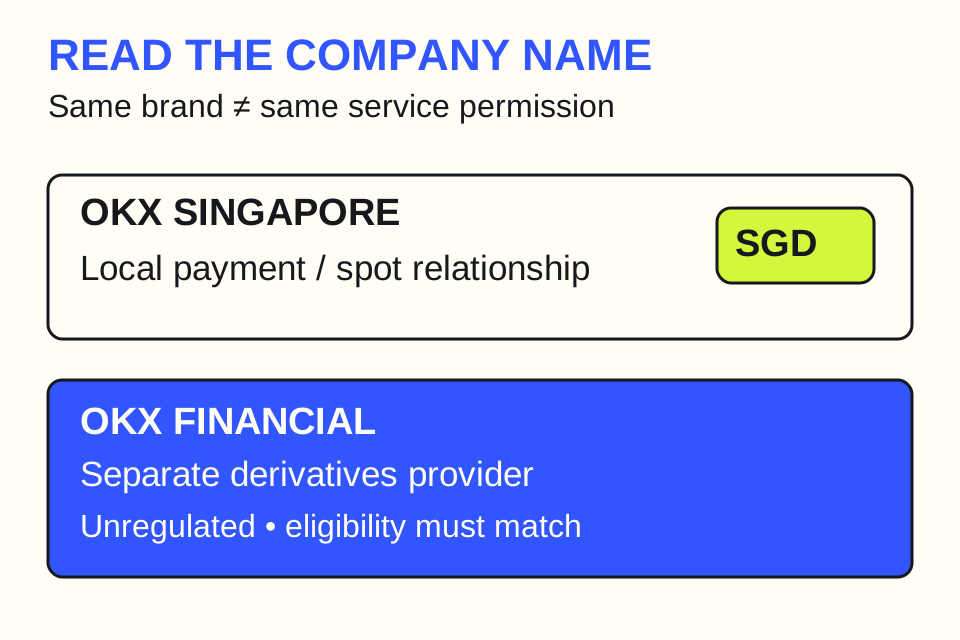
Think of the account as a set of services, not a single permission switch. Successful identity verification answers who you are. A successful SGD deposit answers whether that payment arrived. Derivatives approval answers whether the particular trading service accepts you. Completing the first two does not logically prove the third.
What confirmation is useful for a retail applicant?
Ask which entity will hold the derivatives relationship, whether the current account is eligible without accredited status, and which terms support that answer. Keep the dated response and the terms presented during activation. A generic “Singapore is supported” reply leaves the central question unanswered.
Do not declare yourself accredited just to make an application proceed. Accredited status is a defined category, not a synonym for being experienced with crypto or willing to take risk. If the account screen requires a declaration you cannot truthfully make, the advertised product is not yet an actionable option for you.
An existing user has a slightly different task: inspect the entity and product permissions already attached to their account. A service opened overseas, a legacy product and a newly verified Singapore account may not carry identical terms. The fact that someone else can see a trade button is weak evidence for your own account.
OKX, SGX or Gemini: which difference actually matters?
Once eligibility is established, choose around the crypto position you want. An exchange account offering multiple perpetual pairs solves a different problem from an account offering a small, exchange-cleared crypto-contract range. Neither is automatically superior simply because one looks more familiar or uses a more formal market structure.
OKX for an approved exchange-style crypto account
The Singapore derivatives material advertises perpetuals up to 50x, expiry futures up to 20x and margin trading up to 10x. These are advertised ceilings, not leverage promised on every pair or account. A smaller permitted limit can apply to the exact contract or position size you choose.
The attraction is the product choice: a trader can compare a perpetual with an expiry contract within a crypto-focused service. The limitation is the separate unregulated entity and unresolved public retail wording described above. We would not replace that limitation with a broad “MAS-regulated crypto futures” badge.
SGX for the eligible reader who wants that market structure
SGX launched Bitcoin and Ether perpetual futures in November 2025. The product is relevant to a crypto-futures comparison: it is not a reason to turn this page into a conventional stock-broker guide. Its Singapore trading restriction specifies accredited, expert or institutional customers.
An eligible reader should ask the access provider for the exact contract size, total commission and required margin. Do not compare an SGX quote charged per contract with an exchange fee expressed as a percentage until both describe the same exposure. An apparently small fixed commission can be expensive on a small position, while a percentage tariff grows with position size.
We did not establish a universal all-in SGX retail-access tariff in this review. Consequently, OKX is the more directly documented comparison for an eligible reader seeking a crypto-exchange account; SGX is the alternative to investigate when its clearing and contract structure are the deciding factors. This is a product-fit conclusion, not an unmeasured claim that one has better execution.
Gemini needs an entity-level answer too
Gemini’s global perpetuals eligibility page includes Singapore, but its local Singapore addendum says Gemini Singapore does not facilitate derivatives trading for retail customers. Its Artemis agreement concerns a separate derivatives relationship. Those records should not be collapsed into either “all Gemini users qualify” or “Gemini has no derivatives anywhere.”
For a Singapore applicant, the unanswered operational question is which entity and customer category would supply the actual perpetual account. Until that is confirmed, Gemini is not a stronger recommendation merely because its global country list contains Singapore. Its local spot service can still be evaluated on its own merits.
Perpetuals, expiry futures and margin: choose the right tool
A perpetual is usually the most direct product to investigate for a crypto trader wanting a long or short without a scheduled expiry. An expiry future ends on a specified date. Spot margin means borrowing within a trading arrangement to hold or sell an asset. These distinctions explain the trade more clearly than treating “50x,” “20x” and “10x” as three competing quality scores.
For a brief directional view on BTC, compare the actual perpetual’s execution and funding. For a position planned around a particular future date, inspect an expiry contract and what happens at settlement. For a reader who simply wants to own ETH, a leveraged product may add costs and liquidation mechanics without solving an additional need.
You do not need the maximum to trade a smaller balance
Consider an illustrative 500-USDT margin budget. At 4x it supports 2,000 USDT of price exposure; at 20x it supports 10,000 USDT. A 1% adverse move is roughly 20 USDT in the first case and 100 USDT in the second, before costs. The same market move consumes 4% or 20% of the starting margin respectively.
That is the useful meaning of leverage for a beginner: it changes exposure relative to the money supporting the trade. The number does not improve the prediction or make a stop order guaranteed. Nor is the simple inverse of leverage an exact liquidation formula; the contract’s maintenance requirements and account balance matter too.
Can an existing coin holding offset a short?
Suppose someone holds Bitcoin and opens a Bitcoin short to reduce price exposure. The two positions can offset some price movement, but they remain separate holdings with separate costs and account risks. If the short liquidates, the intended offset disappears. If the spot holding is elsewhere, it may not support the derivatives account automatically.
The practical question is whether the user can keep the intended exposure in place, not whether a diagram makes both arrows cancel neatly. An exchange offering multi-asset collateral also needs a separate review of how much each asset counts towards margin. One dollar of a volatile coin is not necessarily credited as one dollar of usable collateral.
From SGD to a usable trading balance
OKX Singapore’s onboarding guide describes identity verification, a knowledge assessment and SGD funding through PayNow. The existence of that local payment route is useful: it is a clearer starting point than a generic international card purchase. It still leaves the derivatives-eligibility question separate.
The guide describes zero-fee PayNow deposits. “Free deposit” means the payment step has that published charge; it does not make currency conversion, spot execution or a future derivatives trade free. A reader moving SGD into a USDT-margined position needs to price the conversion as well as the eventual contract.
Compare final collateral for the same SGD amount
Take an illustrative SGD 1,000 budget. If one executable route produces 735 USDT and another produces 729 USDT after their stated charges, the first supplies 6 USDT more collateral. The difference is about 0.82% of the better result. These are hypothetical outputs, not exchange rates observed during this review.
This comparison is easier to use than adding several percentages that apply to different stages. Set the same starting SGD amount, the same destination token and the same receiving account, then compare the balance actually available. If a network withdrawal is needed, include it; if funds stay within the approved service arrangement, do not invent a network charge.
What if you already own USDC or USDT?
You may not need to start with SGD at all. Check whether the destination accepts the exact token and network, and whether that asset can support the intended contract. USDC, USDT and a displayed USD estimate are different entries. An accepted crypto deposit is not proof that every balance type is eligible margin.
Avoid an unnecessary conversion merely because a tutorial starts from cash. For an existing crypto holder, the better question is how much accepted collateral arrives after any transfer and conversion, rather than which service has the most attractive SGD marketing offer.
What will an OKX futures trade cost in Singapore?
The September 2026 Singapore accredited-investor schedule publishes regular futures rates of 0.02% maker and 0.05% taker. That is an AI schedule: it is not evidence that a retail account receives every tariff on the same page. Promotional “as low as” rates are also not the correct starting rate for every new customer.
On an illustrative 8,000-USDT position, a 0.05% taker fill costs 4 USDT. Two fills at the same position value cost 8 USDT. A maker entry at 0.02% and taker exit at 0.05% total 5.60 USDT. Actual exit value, tier and contract can change the result.

Why a limit order may still cost the taker rate
The relevant distinction is whether the order adds liquidity or immediately uses an existing order. A buy limit placed high enough to execute immediately can be a taker. If the trading interface offers a post-only setting, understand its behaviour before relying on it: an order that would immediately execute may be cancelled rather than quietly earn the maker rate.
For someone who prioritises getting out of a fast-moving position, avoiding a slightly higher commission is not always the main objective. An unfilled exit can matter much more. Compare order behaviour and likely execution alongside the rate, particularly on a smaller altcoin contract.
Funding can reverse the cheapest choice for a longer hold
Perpetual funding is a separate payment between the two sides of a contract under its rules. If an illustrative 8,000-USDT position pays 0.01% at a settlement, that is 0.80 USDT. Nine such settlements would cost 7.20 USDT. The rate and interval are hypothetical; consult the live contract instead of assuming a fixed daily charge.
That example nearly matches the two-taker commission above. A multi-day trader therefore has a different comparison from someone opening and closing within a short period. Lower execution commission does not settle which contract is cheaper to hold. Nor should a temporarily favourable funding rate be treated as guaranteed income.
Can you get the money back into a Singapore bank account?
Plan the exit in the currency you actually need. Closing a crypto position may leave USDT or another account balance; it does not necessarily leave withdrawable SGD. Conversion and the SGD withdrawal are separate steps, and a balance committed to open positions may not be freely withdrawable.
OKX’s Singapore withdrawal guide covers FAST, MEPS and international wire routes for eligible customers. Choose the method and inspect the live account conditions rather than assuming every bank transfer uses the same limits or timing. The recipient details must fit the provider’s bank-withdrawal requirements.
Gemini provides a useful example of why deposit and withdrawal labels should not be merged: its PayNow FAQ describes free PayNow deposits, but says PayNow withdrawals are unavailable and lists a SGD 3 FAST withdrawal charge. A local payment logo by itself tells only part of the round-trip story.
Small accounts feel fixed costs more strongly
A SGD 3 cash-out is 1% of SGD 300 but 0.1% of SGD 3,000. That arithmetic does not establish which exchange is cheaper overall: the buying or conversion price can outweigh the fixed charge. It explains why a small account should compare the entire intended cycle, not copy a high-volume trader’s choice.
If a withdrawal fails, distinguish the stage. A rejected bank instruction, an incomplete conversion and collateral tied to a position are different problems. Record the transaction reference and the balance type before contacting support. Repeatedly submitting the same instruction without understanding the rejection can complicate the account history.
For crypto withdrawals, token and network must match the receiving service. A successful transfer to a personal wallet also does not establish that a subsequent trading platform is appropriate for Singapore residents. The ability to move an asset and the permission to sell a derivatives service remain different questions.
What protection applies to a leveraged crypto account?
MoneySense distinguishes the risks of payment-token derivatives and explains that products outside MAS regulation do not acquire regulatory protection merely through a provider’s other licensed activity. That is especially relevant when a familiar Singapore brand sits alongside an overseas or unregulated derivatives entity.
For the reader, the useful questions are concrete: who is the contractual counterparty, where is the balance held, what rules allow the provider to close a position, and which complaint process covers this product? A registration number or “regulated” badge that answers a different service question is not enough.
This does not make every unregulated contract fraudulent, and it does not make every regulated contract a good trade. It changes what the customer can rely on if something goes wrong. Price losses, liquidation and a dispute about custody or execution are different problems; a licence cannot eliminate market risk.
A Singapore address and an overseas passport
The OKX onboarding materials distinguish the identity and residence information needed for verification, including relevant Singapore identification or residence records. An expatriate living in Singapore should evaluate the Singapore relationship, rather than use their passport’s home-country ranking to assume access to that country’s derivatives offer.
Likewise, a Singapore citizen genuinely living abroad can face a different provider and product policy. Updating the account to the actual residence is the meaningful change. A temporary trip, an overseas telephone number or a foreign bank card does not establish that residence on its own.
Why Bybit, Crypto.com and DEXs are not automatic alternatives
Bybit’s current service-restricted-country record includes Singapore. Crypto.com’s derivatives geo-restriction page also excludes Singapore from the product described there. A globally popular exchange should not be recommended for this specific account simply because it has a good reputation elsewhere.
Crypto.com can have other Singapore services without making that derivatives restriction disappear. This is exactly why comparing the brand rather than the product causes misleading rankings. If a restriction affects the requested futures account, a spot sign-up is not an equivalent answer to the same question.
A DEX removes some features of a custodial exchange account, but it does not remove the need to understand the service, restrictions, collateral and liquidation. This page does not promote a DEX as a workaround for Singapore customer eligibility. Connecting a wallet is not evidence of local authorisation.
The practical recommendation remains focused: approved users can assess OKX Financial against the eligible SGX alternative; ordinary retail applicants should resolve the OKX account terms before depositing for derivatives. Readers wanting only spot coins can compare local spot products without being sold leverage they never asked for.