









Which crypto exchange is best for futures in Italy?
Kraken leads this review for Italian residents who want a documented European futures account rather than a spot exchange with a leverage advertisement attached. Its Italian product page explicitly describes long and short futures with leverage up to 10x, while the EEA service supports both perpetual and fixed-maturity contracts. The account approval, selected market and applicable limit still control what you can trade.
OKX X-Perps is the closest alternative to examine. It publishes EEA coverage and a European futures product with leverage up to 10x. For an existing OKX user, a suitable contract and competitive live execution can be a stronger reason to stay than a general ranking position is to switch.
| Product | Where it fits | What to establish before funding |
|---|---|---|
| Kraken EEA derivatives | A first futures account, including EUR collateral and a choice of contract duration | European derivatives approval and the actual market's retail limit |
| OKX X-Perps | An alternative exchange account for eligible European futures markets | X-Perps activation, accepted collateral and the selected contract |
| Bybit EU spot margin | Borrowing assets to trade eligible spot markets | Borrowing rate, repayment and available assets; not global Bybit perpetuals |
| Bitpanda Margin | A leveraged long using the underlying crypto asset | Product eligibility and financing cost; the reviewed help page describes long positions |
The first two are our futures shortlist. The others answer different leverage needs and should not be ranked as if they deliver the same contract. A trader who needs a futures short should not discover after depositing that the advertised margin product only supplies a leveraged long.
A large exchange catalogue is useful for research, but it is not a list of equivalent recommendations. We retain wider country coverage separately and explain the product that makes each shortlisted exchange relevant. Italian users should not have to infer derivatives access from a brand's spot licence or an international tutorial.
Kraken or OKX for an Italian futures account?
Where Kraken earns its lead
The clearest benefit is the combination of an Italian-facing futures offer, accepted euro collateral and a choice between perpetuals and dated contracts. If you begin with euros in an Italian bank and want a Bitcoin position, this gives you a relatively direct product to evaluate. You do not first have to build a chain of coin purchases simply to reach a futures wallet.
The recommendation is strongest for a reader who wants to keep the funding process understandable and compare several ways of holding a crypto position. It is weaker if the specific altcoin contract you need is absent, or if the live market is unattractive for your order size. A general first place should never override a missing trading pair.
Kraken's Italian page points EEA clients to a regional derivatives entity. Follow that offer and the associated terms. The same brand's offshore account, spot margin service and European futures account can show different features. An Italian-language interface alone would not establish eligibility, but the explicit regional product information gives this recommendation firmer support.
Where OKX can win the decision
For a trader already using an activated European account, OKX can remove the need to establish a second trading workflow. X-Perps has its own fee and contract documentation. Compare the specific market you intend to trade, including the spread, available size and funding, with the equivalent Kraken instrument at the same time.
A useful comparison is not whether one brand advertises more coins worldwide. It is whether you can enter and exit your intended position at an acceptable total cost. For a smaller order in a major market, ease of managing the position may decide the choice. For a larger or less liquid altcoin trade, the order book can matter much more than a small difference in commission.
We have not measured slippage from funded Italian accounts. That limits any claim about execution quality. Kraken's lead rests on the documented fit for an Italian euro-funded futures trader; it is not a claim of superior fills on every pair or a prediction of better returns.
Can you use 10x crypto leverage in Italy?
Kraken's reviewed Italian futures page and OKX's European X-Perps material advertise leverage up to 10x. Treat those as product maxima, not a promise that every user, coin and position receives 10x. Customer approval, instrument requirements and position size can lower the usable limit.
The familiar 2x retail crypto CFD rule answers a different product question. ESMA has also made clear that a perpetual-futures label does not prevent a product from being classified as a CFD. The right comparison therefore combines the provider's European offering, the actual contract and the protections that apply to it. It is not simply 2x Europe versus 100x elsewhere.
If a tutorial shows a much higher limit, identify which account it uses. An Italian user should not assume that the international interface in a video is the product available after Italian-resident verification. Nor should someone select professional status casually to obtain a higher multiplier; classification can change protections and has its own requirements.
Why the headline maximum can be the wrong filter
Consider a trader with €1,500 available who wants €4,500 of exposure. A product allowing that position already meets the leverage requirement. Moving to another exchange solely for a larger maximum does not improve this trade. The more relevant questions are its cost, the margin buffer, the intended exit and whether the account can hold the chosen collateral.
For a trader seeking €15,000 of exposure from the same €1,500, the risk is materially different. A 3% adverse price change is approximately €450 before costs, equal to 30% of that starting collateral. This is a simplified exposure calculation, not a liquidation threshold. The platform can act earlier when maintenance requirements are breached.
Use the margin preview to see the consequences of the actual order. Increasing size, changing collateral or adding another position can alter the available buffer even when the displayed leverage selector has not moved. That is useful information for an active trader; a global maximum on a comparison card is not enough.
What about Bybit EU, Bitpanda and familiar Italian apps?
Bybit EU does not mean international Bybit futures
The reviewed Bybit EU help material documents spot margin, including borrowed assets and the associated charges. That can be relevant to a leveraged spot strategy, but it should not be presented as automatic access to the worldwide perpetuals product. The country name and the product need to match in the account actually being opened.
Borrowing costs can also behave differently from perpetual funding. Inspect when borrowing starts, what amount remains outstanding and how repayment occurs. An order cancellation does not necessarily erase a charge already incurred. If your strategy is built around futures funding or a particular perpetual contract, a borrowed spot position may not be a substitute.
Bitpanda Margin has a narrower job in this comparison
Bitpanda's reviewed margin help page describes trading the underlying asset with borrowed funds and currently supports long positions. Its separate leveraged products and other asset services should not be mixed into one generic maximum. For someone seeking a leveraged crypto long, evaluate its entry price, borrowing terms and exit cost as a complete quote.
For a short or a hedge requiring a specific futures contract, return to the futures shortlist. A convenient euro interface or familiar consumer brand does not settle that product requirement. This is why Bitpanda can be relevant without displacing the exchanges at the top of this page.
Local branding is useful, but check what it buys
Italian-language support, clear euro funding and a service you already understand can all reduce friction. None alone proves the presence of leveraged derivatives. When evaluating a local coin app or another spot exchange in the wider catalogue, look for the actual contract offer before transferring a futures budget. Educational articles about leverage are not the same thing as a trading service.
Do Italian traders need USDT, USDC or euros?
You do not need to buy USDT as a universal first step. Kraken's EEA collateral table accepts euros. Its regional asset restrictions also mean that a USDT-based walkthrough from another market may not apply to your account. Start from the accepted assets shown in your European derivatives wallet.
A bank deposit in EUR, a dollar-quoted contract and a dollar-valued margin balance describe different things. You can fund in one currency while the platform measures the position in another. That does not automatically mean the euro deposit was converted into a stablecoin, and it does not guarantee the final withdrawal is already sitting in euros.
Why the collateral choice can change the trade
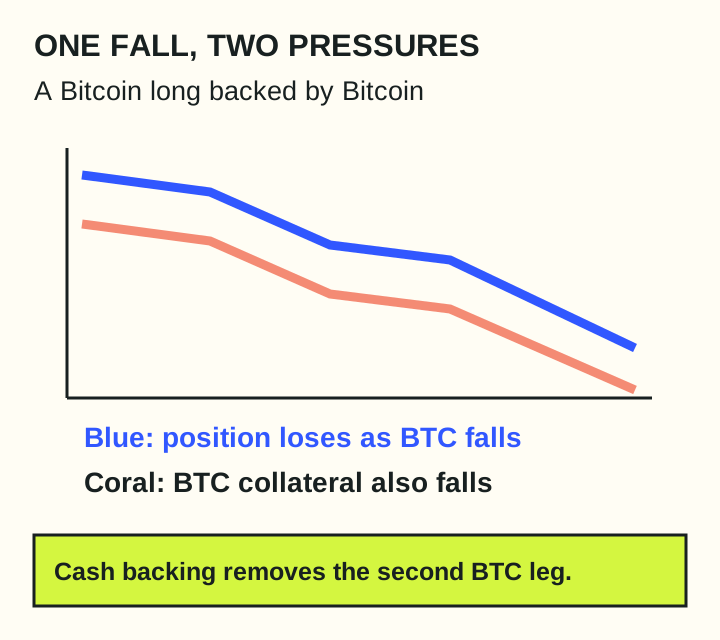
If you support a leveraged Bitcoin long with Bitcoin itself, a fall in Bitcoin can hurt both the position and the value backing it. With cash collateral, that particular combination is avoided, although the position can still lose money and currency valuation can still matter. Choose the collateral for the exposure you want, not just because it is already in your wallet.
Kraken's reviewed EEA schedule values EUR without a collateral haircut, while USDC and BTC receive different haircuts. A haircut means that only part of an asset's value counts as collateral; it is not automatically a cash fee. There can be separate conversion charges, so those columns should not be added together as if they describe the same event.
For example, the reviewed table gives EUR a 0% haircut and USDC a 0.5% haircut. On equal pre-haircut values of $1,000, that means $1,000 versus $995 counts toward collateral before other adjustments. The $5 difference is a smaller recognised buffer, not a $5 withdrawal from your wallet. BTC has a 1% haircut in that table and a separate conversion-fee entry; its market value can also move. These differences matter when deciding whether to transfer existing coins or deposit euros, even when the planned futures position is identical.
That does not make euros risk-free collateral: the position can lose money, and currency valuation can change. It does make the comparison more concrete than choosing whichever token an international tutorial happens to use. Check the current table before funding because accepted assets and adjustments can change.
Sending euros from an Italian account
Use the exchange's current SEPA instructions, including the beneficiary and reference where required. A bank account belonging to a partner or relative is not interchangeable with your own verified funding account. Resolve the sending-name requirements before making a large transfer, rather than hoping the exchange will reconcile a mismatch later.
Compare a direct euro transfer with a card-funded crypto purchase by the usable balance delivered. A card purchase may include a spread, a service fee or a later conversion. A bank transfer may have a processing delay or bank cost. The better route depends on the quote and your starting asset, not on which button says instant.
How much do Italian crypto futures trades really cost?
Separate three questions: what it costs to get money into the account, what it costs to execute the trade, and what it costs to hold the position. This prevents a cheap deposit from hiding expensive execution, or a low commission from hiding a long funding bill.
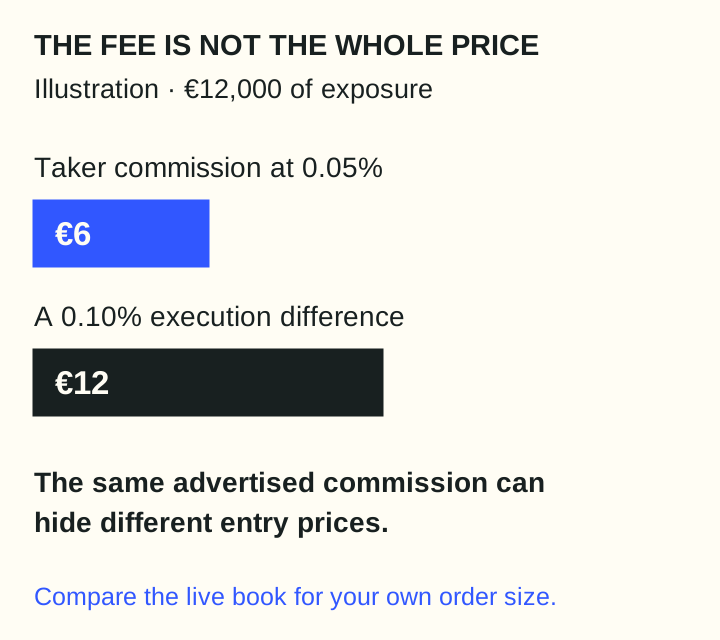
The reviewed starting maker/taker rates for Kraken EEA derivatives and OKX X-Perps are 0.02% and 0.05%. For €12,000 of exposure, that is €2.40 or €6 for one fill at those rates. Closing the position produces another execution charge based on its value at that time. The rates are not charged only on the smaller margin deposit.
Entry and exit price can outweigh commission
Suppose the midpoint price is €60,000 and a market buy fills at €60,060. That €60 difference is 0.1% of the price. On an illustrative €12,000 order, a proportional 0.1% execution difference is €12, before commission. A platform with the same advertised fee can therefore deliver a different result because of spread and available liquidity.
This does not prove either shortlisted exchange is cheaper. It explains what to compare in the live market: the amount you can actually execute near the displayed price. A tiny quote at the top of the book is not a promise to fill a larger order there. Avoid treating a last-traded price as your guaranteed entry.
Holding cost belongs in a multi-day comparison
Perpetual funding can be paid or received and can change while the position is open. X-Perps also has a funding mechanism despite being an expiry futures product. Price the holding period you expect, then consider how the trade would look if the rate moved against you. A favourable payment today is not a locked return for the next month.
For a dated future, compare the contract price with the underlying market and consider whether you will close before expiry or replace it with a later contract. That replacement creates another execution decision. A product with no perpetual funding line can still have a premium and rollover cost.
Is a higher-volume tier worth chasing?
Only count the tier your expected activity actually earns. Trading extra solely to obtain a lower fee creates additional execution costs and market exposure. An Italian retail account does not become economical because its review displays a VIP rate intended for much larger turnover. Base the comparison on your own likely monthly volume and the current schedule.
Can you short Bitcoin without selling your existing coins?
A futures short can reduce the price exposure of Bitcoin you already hold, but its effect depends on the size and the contract. If you own 0.2 BTC and short exposure corresponding to 0.1 BTC, you have approximately reduced the directional exposure by half at that moment. You have not eliminated every risk or created a tax-free coin sale.
A hedge also needs margin. If Bitcoin rises, the coins you hold elsewhere gain value while the short loses. Those wallet gains are not automatically transferred to cover the futures account. A hedge can therefore be forced out even though the combined economic position looks less volatile on paper.
For this use, compare the contract that tracks your holding, the cost of maintaining it and the practical margin buffer. A larger leverage maximum may reduce the initial collateral requirement but also leave less room for a temporary adverse move. A dated hedge can be worth examining when you know roughly when you intend to sell the coins.
Keep the records of the two positions distinct
Record the coin purchase and any eventual coin disposal separately from the derivative's settlements. In Italy that is particularly important because the tax categories can differ. Do not assume that avoiding an immediate coin sale means the derivative's realised profit has no tax consequence. Likewise, the economic loss on one side does not prove it can be offset against the other side in the tax return.
This can be a useful reason to prefer a platform with clear derivative exports over one with a more impressive headline bonus. You need records of what happened, not just a chart of the combined account value. The following tax section explains the distinction without turning the exchange choice into a tax-rate contest.
Are crypto futures taxed at 26% or 33% in Italy?
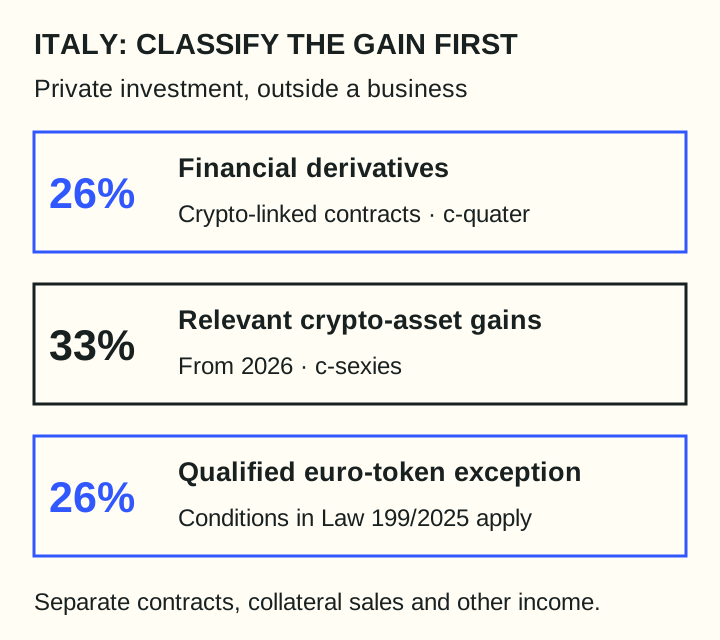
The answer depends on what generated the income. For private investors outside a business, Agenzia delle Entrate's circular 30/E distinguishes financial derivatives referencing crypto from the category covering crypto-asset disposals and similar proceeds. Its section 2.3.2 places those derivative results under Article 67(1)(c-quater), with a 26% substitute tax. The 33% rate introduced for relevant crypto-asset gains from 2026 concerns the separate c-sexies category.
That makes a blanket statement such as all crypto profits are taxed at 33% misleading for a futures guide. It also does not mean that everything inside a futures account belongs at 26%. Selling collateral coins, receiving other rewards and settling a financial contract can generate different records and classifications.
| Activity | Relevant starting point | Why a futures trader should care |
|---|---|---|
| Financial derivative referencing crypto | Circular 30/E: c-quater, generally 26% | Classify the actual contract and its realised result |
| Relevant crypto-asset gains from 2026 | c-sexies, generally 33% | A separate disposal of collateral can fall here |
| Qualifying euro electronic-money tokens | 2026 law provides a 26% exception within its conditions | Not a general exception for all stablecoins or all token activity |
| Business trading activity | Requires its own assessment | Private-investor percentages are not a universal business tax answer |
The 2026 euro-token exception is specific
Law 199/2025 adds a 26% exception for qualifying euro-denominated electronic-money tokens, with conditions covering the euro peg and euro reserves held with authorised EU entities. It also addresses simple euro conversion and nominal redemption. A dollar stablecoin is not brought within that exception merely because you purchased it with euros.
For most readers choosing a futures exchange, the important action is to keep the contract result and the collateral transactions distinguishable. Do not build the trade around a tax rate before establishing the legal product. A lower applicable percentage cannot compensate for a position that loses more money, costs more to hold or does not meet your trading objective.
What to give your commercialista
Provide the exact product name, provider entity, closed trades or settlement ledger, fees, funding and collateral movements. Include opening and closing balances so the records can be reconciled. A screenshot saying total profit cannot show whether the amount includes unrealised positions, transfers or a coin-price gain unrelated to the derivative.
For a simple illustration, €2,000 of taxable derivative gain at 26% produces €520 of tax. The same amount properly classified in a 33% category produces €660. These calculations assume the category and taxable amount are already established; they do not decide eligible losses or replace the full return. The €140 difference is a reason to classify accurately, not to trade a riskier product.
Does an exchange take care of Italian reporting for you?
Do not infer Italian tax withholding from an Italian-language app, local advertising or a European licence. Find out whether the specific service acts as a tax withholding agent for the relevant transactions, and what records it supplies if it does not. Product approval and tax administration are separate services.
Keep an export before changing exchanges or migrating between legal entities. The derivative ledger should let you trace positions, realised settlements, fees and funding; the funding history should explain deposits and withdrawals. Kraken and OKX both document history exports, but different reports can contain different fields. Reconcile them instead of adding two overlapping profit totals.
Profit reporting and asset monitoring answer different questions
Italian reporting can involve both income or gains and monitoring of relevant holdings or foreign financial assets. The details depend on the asset, custody arrangement and reporting regime. Do not assume that a losing year eliminates every reporting obligation, or that the same form treatment applies to a coin wallet and a derivatives contract.
For your adviser, a year-end inventory of actual assets and account balances is more useful than the total face value of every position traded during the year. €100,000 of turnover is neither €100,000 of profit nor necessarily €100,000 of assets held. Keep those three numbers separate when downloading statements.
Withdrawing to an Italian bank
Check the currency that is actually available for withdrawal after closing the relevant positions. Some balance may still be committed as margin, and a displayed euro equivalent is not proof that the entire amount is EUR cash. Convert only where needed, using the quoted rate and charge, then follow the permitted bank-withdrawal method.
For a substantial transfer, retain the original bank deposit and the exchange history linking it to the proceeds. This is a practical source-of-funds record if the bank asks, not a special tax that appears because money crosses a threshold. There is no reason to invent smaller transfers to hide the origin; that would also make your own reconciliation worse.
What changed under MiCA, and what did not?
CONSOB's 2026 notice explains the end of the MiCA transitional period on 1 July. For crypto-asset services, an old registration is not a substitute for the applicable current authorisation. Check the provider's current entity and status rather than relying on a review written during the transition.
MiCA does not supply the whole legal basis for financial derivatives. For a futures account, identify the European investment-service entity and the contract being offered. Kraken's Italian page and OKX's X-Perps documents make those regional distinctions more useful than a generic statement that a brand is regulated in Europe.
This also explains why a platform can remain relevant for coin purchases while its international futures product is unsuitable for the Italian-resident account. We are not removing every other exchange from the country catalogue. We are separating broad coverage from the narrower, product-specific recommendation at the top of the article.
Decentralised interfaces are not treated here as an automatic replacement for a regulated retail offering. A wallet connection does not establish Italian product permission, remove the platform's restrictions or eliminate the need to understand collateral and liquidation. The shortlist concentrates on the documented European centralised products relevant to this review.
Do Italy's autonomous regions have different exchange rules?
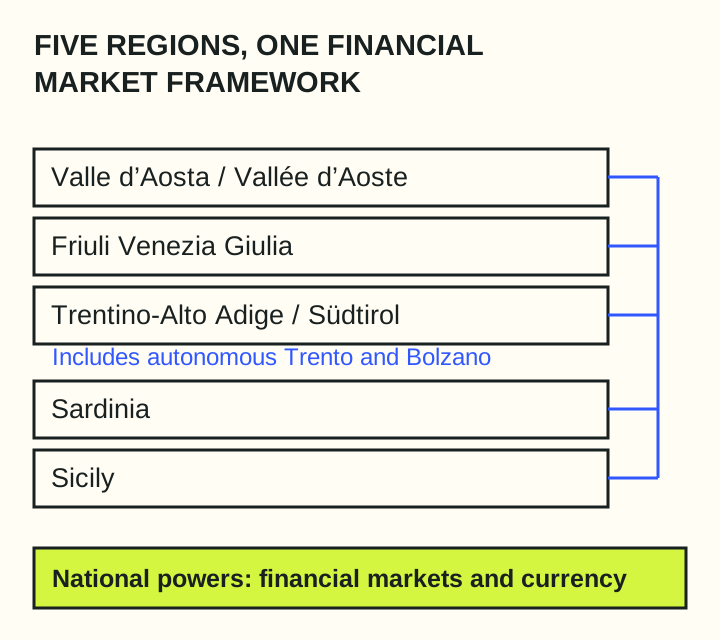
Italy has five special-statute regions: Friuli Venezia Giulia, Sardinia, Sicily, Trentino-Alto Adige/Südtirol and Valle d'Aosta/Vallée d'Aoste. The Constitution also identifies the autonomous provinces of Trento and Bolzano. These distinctions are real, but financial markets, currency and the state's tax system are national competences. Regional autonomy is not a separate permission to use offshore crypto leverage.
For Kraken and OKX, the reviewed eligibility documents do not establish different retail futures lists for those regions. An Italian resident in one of them starts with the Italian/EEA product assessment. We have no basis to publish a higher regional leverage limit or a special local exemption.
South Tyrol, Trentino and language preferences
A German-speaking resident of Bolzano can reasonably prefer German product explanations. That does not make the account an Austrian or German residence case. Use the language that helps you understand the contract while keeping the actual Italian home and tax details correct. Trento and Bolzano's provincial autonomy should not be confused with moving across a national border.
Valle d'Aosta and Friuli Venezia Giulia
Here the useful distinction is a real cross-border living arrangement, not a new set of regional futures rules. Someone working across a border should establish where they actually reside for the provider's account, and separately obtain the appropriate tax treatment. A French-language interface in Valle d'Aosta or a Slovenian bank relationship near Trieste does not independently decide either question.
Sicily and Sardinia
Island residence does not create a separate crypto exchange country selection. Apply the same product comparison as mainland Italy. Local bank costs or the documents available to an individual may differ, but those are account circumstances to check, not a reason to fabricate a Sicily-only or Sardinia-only exchange ranking.
What about Livigno, Campione and living outside Italy?
Livigno and Campione d'Italia have special customs or VAT treatment, which can cause confusion in discussions of crypto tax. The European Commission's territorial table shows Livigno outside the EU customs and VAT areas, while Campione is within the customs area but outside the VAT area. Those are not blanket exemptions from tax on personal trading gains.
Do not translate duty-free shopping rules into a tax-free futures claim. Neither location should be selected as Switzerland merely because of geography or a banking connection. Use the actual residence accepted by the provider and obtain advice on any specific local tax relief instead of extending a VAT exception to an unrelated financial transaction.
San Marino and Vatican City are separate states, not two more Italian autonomous regions. Living in either is different from living in an Italian town nearby. Our separate country guides cover those residence cases; employment, nationality and an Italian bank account are not interchangeable with residence.
An Italian citizen genuinely living abroad should investigate the exchange offering for the country where they live. Returning to Italy can change the relevant entity and product access, so review open positions before an account migration. Conversely, a foreign citizen resident in Italy should investigate the Italian offering rather than assume their passport unlocks the product range of their country of origin.