
















Which exchange can a Seychelles resident consider?
OKX: a focused USDT futures account
Our first candidate for existing USDT, with its Seychelles entity and application status examined below.
Read the verdictKraken: retain eligible cash collateral
An alternative for approved international accounts funded in a supported cash currency.
Read the verdict| Platform | Our assessment | Decision |
|---|---|---|
| OKX | No Seychelles exclusion found in the reviewed location policy; separate product approval still applies | First candidate for a USDT-based setup. |
| Kraken | Seychelles is absent from the reviewed international derivatives exclusion list | Compare if you already have supported cash or prefer its account tools. |
| Bybit | Its policy excludes persons in Seychelles, with a distinct IBC exception | Do not use for an ordinary Seychelles personal account. |
| MEXC | FSA identifies an unlicensed operator and enforcement action | Not recommended for this resident shortlist. |
Check the entity and product offered to your verified account before funding it. Eligibility under an exchange’s country policy does not establish a final Seychelles licence.
Why start with OKX for USDT futures?
If your intended trading funds are already USDT, a USDT-settled perpetual gives you a straightforward way to track the trade: margin, costs and the contract result can be read in the same asset. This is the case for our first recommendation. It is a practical preference for that starting balance, not a claim that OKX is the only exchange offering stablecoin futures.
OKX’s terms identify Aux Cayes FinTech for eligible users outside its specified regional entities. The FSA register names Aux Cayes, trading as OKX, with an application under assessment dated 18 July 2025. Those documents make it possible to identify the company and its stated regulatory stage. They do not let us relabel a pending application as a final licence.
Before relying on that entity match, read the company shown in your own account agreement. A visitor redirected to another regional product should not assume this analysis follows them unchanged. The product, the contracting company and the resident’s eligibility must line up.
Our suggested starting setup is modest: choose the intended USDT contract, allocate only its trading balance, and read the amount at risk before opening. There is no benefit in enabling a more complicated collateral mode solely because the platform offers it. You can assess the account without accepting the maximum leverage offered on screen.
When is Kraken a better fit?
Kraken is worth prioritising when you already hold a supported cash currency and want to use an eligible international derivatives account. Its collateral list includes cash as well as crypto assets. That can save a needless spot purchase merely to obtain a particular stablecoin, although funding-provider access and account approval still need to be satisfied.
The international derivatives eligibility page requires full verification for personal clients and a different verification standard for businesses. Seychelles is not on that page’s restricted-region list. This is evidence about Kraken’s policy, not a licence from the Seychelles regulator. Do not confuse Kraken’s US futures service with the international account discussed here.
The trade-off is how the account values collateral. A balance in another currency can change in US-dollar value while Bitcoin is flat; crypto collateral can fall at the same time as the position. Pick the wallet because it suits the funds you actually have, not because a long asset list sounds more sophisticated.
There is no basic execution-fee winner here
The regular examples reviewed for both OKX and Kraken start at 0.02% maker and 0.05% taker. On equal 5,000-dollar entry and exit values, two taker fills total 5 dollars, while two maker fills total 2 dollars. That comparison excludes funding, conversion, spread and special-market rates.
This tie is useful: it means a claim that one is clearly cheaper on every trade would be misleading. If your money is already in USDT, the simpler settlement setup can favour OKX. If your money is already eligible cash on Kraken, the cost of moving and converting it can favour staying. A one-off transfer cost should not be hidden behind a table of tiny trading percentages.
Does a Seychelles company mean a locally approved account?
No. A company registration tells you where an entity exists. A regulatory permission concerns the services it may provide. Customer eligibility tells you whether it will serve you. Seychelles is a particularly important place to keep those questions separate because several globally known exchange brands have corporate connections here.
The FSA’s VASP page contains company entries expressly labelled as applications under assessment. Its explanatory note describes transitional treatment for qualifying pre-existing applicants. Read the status column and note together rather than interpreting the page title as a blanket approval of every listed company.
The FSA also explains that a Seychelles-incorporated company may need a VASP licence even if its activity is conducted elsewhere. That makes the company’s connection to Seychelles relevant to supervision. It does not automatically make a product available to a person who lives in Victoria or on Praslin.
Why Bybit is a different answer for a resident
Bybit’s current restrictions identify persons in Seychelles as prohibited parties, while setting out an exception for a qualifying international business company. The exception concerns a different kind of customer. A personal account is not made eligible by selecting a business label or using a company name that does not reflect the real owner.
An existing legitimate business would need its own corporate onboarding and beneficial-owner checks. This personal guide does not treat company formation as a shortcut around a residency restriction. For an ordinary resident comparing accounts today, the direct answer is to leave Bybit out of the personal shortlist.
Why is MEXC excluded from our recommendation?
The FSA statement dated 26 May 2026 identifies MX Global Ltd as operating MEXC without the required VASP authorisation and says no related licence application had been received. It also distinguishes that company from the former MEXC Global Ltd, which had been dissolved. These are named entities and a specific regulator finding, not a deduction from an old logo or address.
The resulting recommendation is simple: do not choose MEXC on the assumption that its Seychelles connection gives you locally supervised protection. The record remains visible with the enforcement issue attached, rather than disappearing from the database. The two claims “the website can open” and “this is an appropriate locally supervised choice” are plainly different.
If you already have funds there, the priority is understanding your account’s withdrawal and dispute position. Do not open a larger leveraged position to try to recover an earlier loss, and do not pay an unsolicited intermediary who claims that the company’s registration number guarantees recovery.
How expensive is funding from a Seychelles bank?
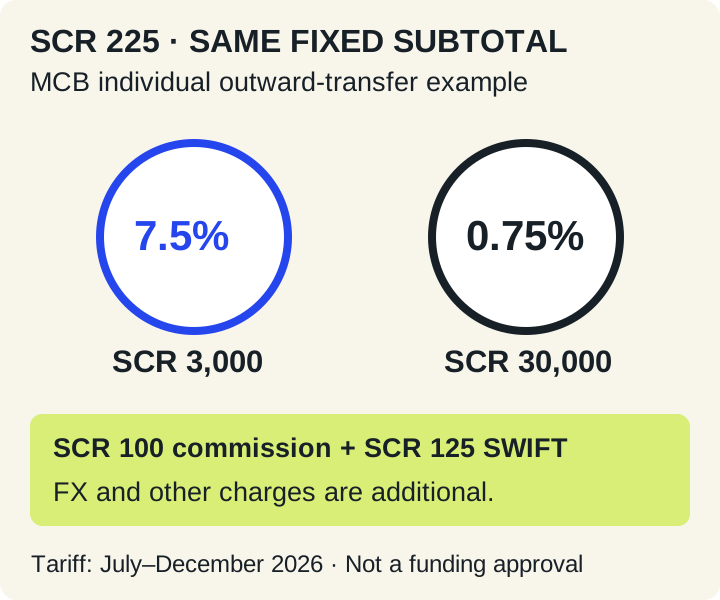
MCB Seychelles’ July–December 2026 individual tariff is a useful local example. It lists a SCR 100 commission plus SCR 125 SWIFT charge for an outward international transfer, with correspondent charges and an additional same-day component where applicable. The business tariff elsewhere in the same PDF is different; using its percentage fee for a personal account would give the wrong answer.
The identifiable SCR 225 fixed subtotal is already 7.5% of a SCR 3,000 transfer and 0.75% of a SCR 30,000 transfer. Neither is an all-in quote: exchange rates, correspondent charges and the recipient’s fees can add more. It illustrates why repeatedly sending small amounts can cost more than the execution of the futures trades themselves.
Would a card be cheaper?
The same individual tariff lists a 5% foreign-exchange conversion fee in its card section. A foreign-currency purchase worth SCR 3,000 before that charge would add SCR 150 if the fee applies. That is not enough to conclude “use the card”: the exchange’s checkout price, any purchase charge and the bank’s permission for that merchant also matter.
For this decision, ask for two complete quotes for the same amount received, one by the supported bank route and one by an eligible card purchase. Reject a route that does not accept the real purpose or sender, even if its arithmetic looks cheaper. A bank tariff describes pricing, not approval of every beneficiary.
Can profits be withdrawn directly in Seychelles rupees?
Do not assume so. A derivatives profit can be denominated in USDT or dollars while the eventual bank account is in SCR. The conversion from a trade result to spendable rupees is a separate operation. The exchange’s supported withdrawal currency and provider determine the first leg; your bank determines the local receipt and conversion.
Kraken publishes cash deposit and withdrawal tables with different currencies, providers, minimums and geographic conditions. A row headed “worldwide” still has conditions attached to that provider and account. Confirm the available method in your account before using a general table to plan a large payment.
If you hold both an SCR account and a foreign-currency account, compare which one the withdrawal provider can actually pay. A supported foreign-currency receipt may let you choose when to convert, but it does not abolish conversion costs. A local SCR account number is not interchangeable with international bank details for another currency.
A small successful withdrawal is a useful operational check when the route is permitted, though it does not guarantee that a larger transfer will avoid additional review. Save the exchange’s withdrawal reference and the bank’s credit advice together. They connect the amount sent, the currency received and any deductions without relying on a screenshot of a trading profit.
Who handles a blocked withdrawal or account dispute?
Start by identifying where the failure occurred. A futures order that closed at an unexpected price is an exchange trading dispute. A transfer marked completed by the exchange but absent from your bank needs its payment reference traced. A rejected identity document belongs to account verification. Sending all three as “my money disappeared” makes it harder for the receiving team to act.
For matters within the FSA’s remit, its complaint guidance says to complain to the entity first and allow the prescribed response periods, including at least two business days for acknowledgement and twenty-one business days for determination. Escalation requires the complaint form and supporting records. This process is not a promise that the regulator will reverse a trade or pay compensation.
A useful complaint is short and specific: the account entity, the date, the amount, the transaction or order identifier, what the provider said and the remedy requested. Attach the original messages and transaction history. You should never provide a wallet recovery phrase as part of an account complaint.
Keep unlicensed-operator reporting separate from the licensed-firm complaint process. The MEXC statement explains the limits on FSA intervention for that operator. A filing may help an enforcement record without giving the authority the ability to recover an individual balance.