








Which crypto futures exchange makes sense in Finland?

Kraken is the most useful starting point for a Finnish resident who wants a dedicated crypto derivatives account with both perpetual and dated contracts. Its European service publishes its collateral rules, commissions and account requirements separately. That makes it easier to compare a specific BTC or ETH trade without borrowing figures from an offshore version of the platform. Account approval is required; the recommendation is about product choice, not a promise about your tax result.
OKX X-Perps suits someone who already trades through the European OKX account and prefers to keep eligible positions there. The entry maker and taker percentages match Kraken’s published starting rates. Choosing between them therefore calls for something more useful than declaring one “cheaper”: compare your actual market, the collateral you intend to use and the cost of holding the position.
Finland adds a decisive complication. Vero’s rules can tax profitable derivative transactions while disallowing the corresponding losses. A service can be properly authorised and still offer a contract with unattractive Finnish tax treatment. For frequent traders, that question deserves an answer before meaningful money enters the derivatives wallet.
| Option | Where it earns a place | What must be settled first |
|---|---|---|
| Kraken EEA derivatives | Perpetual and dated crypto contracts; documented euro collateral | Finnish treatment of the actual contract and trading venue |
| OKX X-Perps | A European OKX workflow with funding-based crypto contracts | Account activation and the contract’s tax classification |
| A qualifying listed crypto future | Worth investigating when deductible losses are essential | Whether that exact market meets Vero’s requirements; broker permission and contract size |
A qualifying market can matter more than a large contract catalogue when losing trades need to offset winners. Someone making a handful of directional trades and someone running hundreds of winning and losing positions have different exposure to Finland’s rules. A useful exchange comparison must show that difference rather than rank every account by its largest leverage button.
Can you owe Finnish tax after losing money overall?
Yes, where the contracts fall under Vero’s non-deductible-loss treatment. Consider a simplified year with €8,000 of profitable CFD transactions and €9,000 of losing ones. The trading result is minus €1,000, but the winning transactions can still produce €8,000 of taxable capital income. At 30%, and ignoring other income or personal adjustments, that is €2,400 of tax. The combined cash impact becomes minus €3,400.
This is why a dashboard’s annual net result is insufficient. It may subtract every losing trade correctly for trading purposes while producing the wrong starting point for a Finnish tax calculation. There is no contradiction between a red annual performance chart and a tax bill: the two calculations can include different transactions.
Vero explicitly separates CFDs from ownership of crypto assets. Its broader derivatives guidance also distinguishes contracts traded on qualifying regulated or equivalent markets from other contracts. The practical response is to establish which category your instrument belongs to, not to relabel a losing perpetual as a coin sale.
For example, a trader closing numerous small positions can have much larger gross winnings and gross losses than their final balance suggests. Download both sets. If the exchange report offers only a single net figure, export individual trades or settlements as well. Those records reveal the potential tax exposure before the annual return makes it an expensive surprise.
Does a European licence make futures losses deductible?
No automatic connection exists between those two questions. The licence identifies the permitted service and responsible firm. Finnish loss treatment depends on the instrument and, for the relevant derivative rules, the market on which it trades. “Regulated company” and “qualifying regulated market” are not interchangeable descriptions.
A useful request to the exchange names the exact contract and asks for the legal counterparty, execution venue and product document. A reply linking only to its general MiCA authorisation leaves the tax question unanswered. The next step is to compare those documents with Vero’s derivatives guidance, which also discusses equivalent markets outside the EEA.
What a Finnish trader should have confirmed
Ask whether gains and losses from this named product receive the treatment applicable to qualifying exchange-traded futures or to other derivatives. Include how the contract settles and whether settlement is cash or crypto. These are relevant details because they change the calculation; a list of every token supported by the exchange does not.
Where substantial recurring activity depends on the answer, Vero offers a paid advance ruling for the applicant’s own tax circumstances. A complete application is more useful than a general question asking whether “Kraken is tax deductible.” Attach the actual contract and venue information. An exchange’s customer-support team cannot issue a binding Finnish tax decision.
That unresolved classification limits the strength of any unconditional futures ranking for Finland. Kraken remains a practical crypto-account choice, but we would not present it—or OKX—as a verified way to obtain deductible losses across all its products. A trader who cannot make the strategy work without those deductions should resolve this point before scaling up.
How much crypto leverage can Finnish residents use?
The European product matters more than the global exchange advertisement. OKX markets X-Perps with leverage up to 10x, subject to the instrument and account. Kraken’s European contract specifications distinguish account categories; a professional maximum is not a promise to a newly approved retail customer. Check the live initial margin requirement for the exact position size.
European CFD restrictions are a separate consideration. ESMA’s February 2026 reminder says that products marketed as perpetual futures can fall within the CFD measures when they meet the definition. Crypto CFDs subject to those measures have a 2:1 retail leverage limit. That does not establish a universal 2x limit for every instrument called a future, nor does an exchange’s 10x headline override product restrictions.
If your ticket requires €400 of initial margin for €2,000 of exposure, the opening ratio is 5x. It is not 10x just because the product family advertises “up to 10x.” If a larger position requires proportionately more margin, the usable leverage falls further. The amount shown when the account approves the order is the relevant figure.
Do not apply for professional status merely to make the multiplier larger. That classification can change protections and has its own requirements. For a Finnish trader, increasing turnover or leverage also magnifies the importance of the tax issue above: market losses and a separate tax obligation can consume capital at the same time.
What does a euro-funded crypto trade actually cost?
At their published entry tiers, Kraken EEA derivatives and OKX X-Perps each list 0.02% maker and 0.05% taker commissions. Those are percentages of the position traded, not percentages of the margin deposit. They do not include every possible cost, and they do not prove that the two venues will execute at the same price.
For a hypothetical €6,000-equivalent position, opening and closing at 0.05% costs approximately €6 in commission if the closing position value is unchanged. Providing liquidity at 0.02% on both sides costs approximately €2.40. The €3.60 difference is real, but an unfilled entry or a worse exit can outweigh it. These examples translate the fee into euros for readability; actual billing follows the product’s stated currency.
Holding a position changes the comparison
A funding-based contract adds payments between the long and short sides. The rate can change direction. If a hypothetical €6,000-equivalent position pays 0.01% at each of six funding events, the total is €3.60, assuming the position value stays constant. That is an illustration, not a current rate forecast or a guaranteed cost over two days.
A dated contract introduces expiry and may trade at a premium or discount instead. It should not be described as free financing simply because there is no identical recurring funding entry. Compare the quoted contract price and the intended holding period. For a position kept only briefly, execution can dominate; for a longer hold, the financing arrangement can change the preferred contract.
Should you use euros, stablecoins or Bitcoin as collateral?
For someone receiving income and paying bills in euros, starting with EUR cash avoids an unnecessary purchase of a token purely to fund the account. Kraken’s published European collateral table gives EUR cash a zero haircut. A haircut is the reduction in value recognised for margin; it is not a fee deducted from every deposit. The contract can nevertheless calculate profit, loss and charges in another currency.
Bitcoin collateral introduces a different problem. If you use BTC to support a long BTC position, falling Bitcoin can damage both the trade and its backing. A euro-funded position avoids that particular double exposure, although its losses still reduce available margin. The choice is about how the account behaves in the move you are trading, not about which asset has the most familiar ticker.
Vero’s crypto guidance discusses another consequence: a derivative settlement involving crypto can also involve a crypto disposal. The derivative result and the coin transaction may need separate treatment. Keep the coin’s original acquisition information rather than assuming that the exchange’s realised-P&L field describes everything taxable.
For an existing Finnish Bitcoin holder, that can favour keeping long-term coins separate from the derivatives account. You retain the original purchase record and choose deliberately how much cash to allocate to the new position. This is an operational preference, not a claim that moving between your own wallets creates a sale or that euro collateral makes futures tax-free.
Funding from a Finnish bank without an extra conversion chain
Direct EUR funding is the first route to compare when the approved exchange account accepts your bank transfer. Use the receiving details generated inside that account. A saved beneficiary from an old service or an earlier account migration may point to different instructions. A euro amount sent successfully to a bank is not necessarily a credited derivatives balance.
The practical comparison is between credited trading funds and the total amount leaving your bank. If an instant payment carries an additional charge but an ordinary transfer is free, the value of speed depends on whether the position actually needs to be opened immediately. Do not buy and transfer a token solely because a video shows that workflow for customers outside Europe.
Finnish services such as Coinmotion can be useful for buying or selling coins, but adding a local intermediary is not automatically a better futures route. Its own help centre separates trading charges, crypto transfer fees and a €0.90 euro withdrawal fee. A domestic deposit can be convenient while the extra coin purchase and outbound transfer still make the full journey more expensive.
For example, compare €1,000 credited directly with the amount remaining after a local coin purchase, a network transfer and any conversion at the destination. Use live quotes for that comparison; a low withdrawal fee alone says nothing about the purchase spread. If you already own the accepted coin, the calculation is different because the initial purchase step has already occurred.
Is borrowed spot margin different for Finnish tax?
It can be, and this is a more useful distinction than simply asking whether the trade uses leverage. Vero separately describes margin transactions in which borrowed funds actually buy or sell crypto assets. The borrowing does not turn the whole activity into a derivative merely because the interface displays a multiplier.
For a genuine leveraged coin purchase, the full purchase amount forms the acquisition cost, including the borrowed portion. The later sale is assessed against that acquisition cost under the relevant disposal rules. Vero also addresses associated trading and borrowing costs. This differs from treating a contract payout as other derivative income, where losses may be non-deductible.
A simplified long illustrates the distinction. You contribute €600 and borrow €1,400 to buy €2,000 of a coin. It later sells for €2,200, with €25 of qualifying transaction and borrowing costs. The arithmetic is €175 before the applicable personal tax calculation. It is not €1,600 of profit just because only €600 initially came from your own cash. The €1,400 loan still has to be repaid.
Do not identify the product from its button label
An app can use the word “margin” to describe money supporting a future, even though no borrowed spot purchase occurs. Inspect the trade confirmation: did the account acquire the coin and incur a loan, or did it open a derivative contract? The distinction must be real. Renaming a perpetual in your spreadsheet does not change its treatment.
For a Finnish trader seeking modest leverage on an available spot pair, this is a worthwhile alternative to investigate alongside futures. Compare the borrowing rate and permitted holding period, and confirm that the provider offers the service to your account. We have not assigned a universal borrowing rate or a separate tax approval to every exchange in the catalogue.
Borrowing also introduces operational limits that a perpetual trader may not expect. The desired asset may not be borrowable in the requested amount, and carrying a loan has a cost even if the market barely moves. Select it because the actual transaction and after-cost result fit the plan, rather than assuming it is automatically the cheaper or simpler substitute.
Build a Finnish tax record from the exchange exports
The useful record has separate columns for the product, settlement date, result, fees, funding and settlement asset. A transfer to your bank belongs in the cash-movement record, not in place of the trade result. Otherwise a profitable position left on the exchange can disappear from your tax working papers simply because no withdrawal occurred.
Kraken provides account-history exports and derivatives logs. OKX documents trade and position histories, including funding-related fields. Neither feature is a finished Finnish tax assessment. The advantage is that you can reconstruct what happened and then apply the relevant Finnish treatment, rather than guess from screenshots of a final balance.
| Record | What it establishes | What it cannot establish alone |
|---|---|---|
| Contract and venue document | Which product was traded | Whether every loss is deductible in Finland |
| Trade or settlement history | Winning and losing outcomes | The original cost of coins used later |
| Funding and fee history | Additional amounts paid or received | Your full personal capital-income position |
| Coin and cash transfers | Movement between wallets and bank accounts | A substitute for realised trading results |
Keep an untouched export and a separate working copy. When software combines accounts, check one winning trade, one loss, one funding payment and one internal transfer manually. A transfer counted as income twice can distort the result as much as a missing losing trade. This is a small sample check with a clear purpose, not a requirement to read thousands of entries by hand.
For foreign CFD profits, Vero directs individuals to the foreign capital-income area of MyTax. Do not automatically enter every crypto-related number in the coin capital-gains section. Use the return route corresponding to the actual instrument and retain the calculation supporting it.
What changes with Finnish crypto reporting in 2026?
Crypto service providers covered by Finland’s new reporting rules collect customer and transaction information from 2026. Vero’s July 2026 guidance describes first annual returns in 2027 and international information exchange for that first reporting year. This expands the information reaching the tax authority; it does not remove your responsibility to check the personal return.
That distinction matters when moving between a Finnish coin service, an overseas derivatives provider and a self-custody wallet. Each organisation can see only its part of the sequence. One may know the sale proceeds but not the earlier acquisition cost; another may record a transfer that your portfolio software has already matched. Your own records connect the pieces.
A request for a Finnish tax identification number is therefore not evidence that the platform will calculate and pay all your taxes. It can be part of account identification or reporting. Keep the distinction clear when comparing services: “collects tax details,” “provides a report,” and “withholds Finnish tax” describe three different functions.

When a report appears automatically in MyTax, compare it with the actual transactions and correct errors through the appropriate process. Do not leave an incorrect figure untouched merely because it came from a provider. Equally, do not delete a real gain because the proceeds remain in a stablecoin rather than in your Finnish bank account.
Finnish residents abroad and newcomers trading from Finland
Exchange residence and tax residence need not change on the same day. A Finnish citizen moving abroad can remain within Finland’s tax-residence rules for the departure year and the following three years unless the relevant conditions for earlier non-residence are met. Treating a new rental address as instant removal from Finnish taxation can therefore produce the wrong trading budget.
A foreign citizen arriving in Finland has a different starting point. The appropriate question is when Finnish tax residence begins under the actual facts and any applicable treaty. Their existing overseas exchange account may also need an address update and migration to a European service. Those are separate processes, with potentially different effective dates.
For an open futures position, retain a balance and position statement around the move. That gives an adviser something concrete to work with if the countries use different valuation or timing rules. It also lets you verify whether the provider transferred the position, required closure or changed the collateral arrangements. A new login screen alone cannot explain the financial effect.
The same Finnish income-tax questions apply whether the trader lives in Helsinki, Tampere or a smaller municipality. We have not found a local city-based permission that grants different exchange leverage. Differences in an individual’s tax status or account approval are relevant; inventing a separate futures regime for every region would make the answer longer without making it better.
A small-account trial that tests something useful
Start by confirming that the desired European contract is enabled, then inspect the minimum order size and the fee preview. A successful spot purchase is not a test of the derivatives product. Nor is an empty demo account proof that real deposits and withdrawals will follow the same path.
For a small live trial, the useful output is a complete cycle: the deposit is credited, the chosen order behaves as intended, the position closes, the records export correctly and an allowed withdrawal reaches the intended account. Use a size whose loss you can absorb. The purpose is to test the service chain, not to manufacture trading volume or meet a promotional target.
An exit deserves particular attention. Check whether the stop watches the last traded price or a reference price, and whether the resulting order can execute at a worse level during a fast move. You need not memorise the matching engine. You do need to understand why a stop shown on screen is not necessarily a guaranteed fill at that exact number.
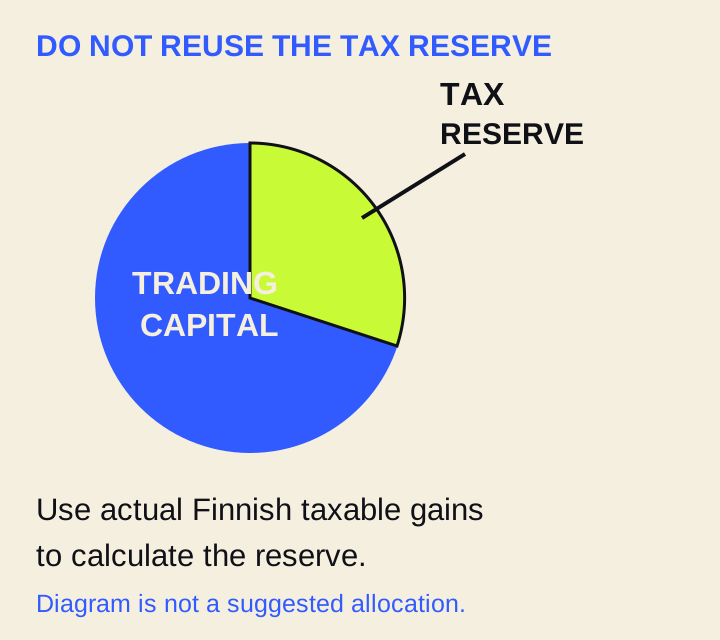
Finally, separate money reserved for a possible tax bill from reusable trading capital. In Finland this is more than routine budgeting: the winning-trade total can remain relevant even after later losses. A strategy that requires every euro to be immediately reinvested deserves a second look once that obligation is included.
When should a Finnish trader delay opening the position?
If a strategy relies on offsetting frequent losses, the exact Finnish tax classification is a prerequisite, not a detail to sort out after trading. Use the contract and venue documents to resolve it. Once that answer supports the strategy, compare Kraken and OKX on the actual market, collateral and holding period. The attractive account is the one that works after Finland’s tax calculation, not just on the exchange’s profit chart.