Lowest Fee Crypto Futures Exchanges
Compare the price of a completed trade, with real account conditions and a matched BTC funding study.
Short answer
Paradex Retail and Lighter Standard tie at zero normal trading commission for qualifying manual orders. Deribit has the lowest confirmed regular CEX taker profile here. For USDT-funded BTC trades, compare Binance and OKX, then include funding over the intended holding period.
Visit ParadexThe shortlist by fee profile
Editorial choices for eligible accounts. Check your country for the product available to you.
0% normal Retail commission; interactive-order conditions apply.
Read the comparisonStandard is free; Plus and Premium use different tariffs.
Read the comparison0.015% / 0.035% Standard futures rates; confirm the required settlement asset.
Read the comparison0.015% / 0.045% base validator-perp maker/taker.
Read the comparisonHigher taker commission, lower long funding in our seven-day sample.
Read the comparisonSeparate trading commission from conversion and collateral charges.
Read the comparisonCrypto futures fee comparison: the rate and the conditions
The lowest published trading commission in this comparison is zero, offered by Paradex Retail orders and Lighter Standard accounts. Those are useful choices for someone placing ordinary manual orders in an eligible location. Neither result says that every trade costs nothing: the execution price, funding and movement of collateral still affect the amount left in your account. For a centralized derivatives account, Deribit Standard has the lowest regular two-taker commission among the confirmed profiles below, while Binance and OKX provide the straightforward USDT comparison.
| Platform / profile | Maker | Taker | Scope |
|---|---|---|---|
| Paradex Retail | 0% | 0% | Qualifying Retail perpetual orders |
| Lighter Standard | 0% | 0% | Standard account; normal orders |
| Deribit Standard | 0.015% | 0.035% | Futures/perpetuals; excludes collateral, delivery and special-order charges |
| Hyperliquid | 0.015% | 0.045% | Base validator-operated perps; no staking discount |
| OKX | 0.02% | 0.05% | Regular level 1 futures; regional terms apply |
| Binance | 0.02% | 0.05% | Regular USDⓈ-M USDT; no BNB discount |
| Bybit | 0.02% | 0.055% | VIP 0 regular perpetual/futures; excludes special zones |
| Kraken | 0.02% | 0.05% | Entry derivatives tier; excludes conversion/collateral charges |
This table compares entry-level accounts without token holdings, negotiated terms or temporary rewards. Maker and taker describe how a fill reaches the order book, not whether you clicked a button labelled Limit or Market. A limit order that immediately matches another order can pay the taker rate. The official Bybit schedule separates its regular futures rate from spot and special trading zones; we use the regular futures row here.
Read the account column before comparing percentages. A Paradex order submitted through its normal API is Pro by default; an interactive API order can receive Retail treatment under its documented limits. A Lighter Premium account has a different tariff from Standard. Putting the free rate beside every trading channel would produce a misleading result even though the headline itself came from an official website.
All calculated examples use a 10,000 USDT or dollar-equivalent position at entry and the same value at exit, unless stated otherwise. This keeps the comparison about cost rather than a price prediction. A real closing fee changes with the closing value. We assume dollar parity for USDT and USDC in these examples; swapping between them is a separate transaction with its own price.
Why MEXC and Gate need separate treatment
MEXC belongs in a low-fee investigation, but a single universal rate does not describe its current offers. Its June new-user announcement describes a verified-user allowance on selected contracts, followed by region-dependent prices. That is a conditional promotion, not a lifetime zero-fee account. Its API notice has a separate problem: the adjustment table and worked example disagree. We show that conflict rather than quietly choosing the cheaper number.
Gate's public fee page is dynamic and differentiates product categories and Points deductions. A fee quoted for a stock-linked perpetual is not evidence for a BTC perpetual. Its collected BTC_USDT contract response supplies default fee fields, but these do not establish the account's final VIP or Points-adjusted tariff. Gate’s contract default is shown separately from confirmed account prices.
For a manual order, the usable comparison is the row matching your account class. For automation, use the separate API price and throughput conditions below. If a promotion is volume-capped, price the intended volume above the allowance as well as the free portion. That separates three genuinely different bills instead of blending them into a single “average futures fee.”
Low-fee platforms: what each price actually buys

Paradex: our first stop for manual, commission-free perp orders
Paradex earns the lead for the manual fee profile because its published Retail schedule charges neither a maker nor a taker commission on perpetuals. That removes the usual choice between a cheaper passive entry and a more expensive immediate exit. It is particularly useful when you want to close at market rather than leave an exit waiting on the book. This is a fee-based recommendation, not a claim that Paradex always supplies the best executable price.
The condition matters. Retail is an order classification, not a permanent promise attached to your name. Paradex's classification rules distinguish website and qualifying interactive orders from normal Pro API flow. Retail orders face a speed bump and lower activity limits. An occasional manual trader may accept that trade-off; someone continuously replacing quotes should compare the Pro schedule instead. This is why the same platform can be attractive for a person clicking through a few trades and less competitive for that person's automated strategy.
Against Lighter Standard, both start at zero commission, so fees alone cannot break the tie. Compare the exact coin, the price shown for your order size and the collateral route. We place Paradex first for this manual shortlist while showing Lighter as an equal commission alternative. Choose Hyperliquid instead when the market you need or its executable quote outweighs the commission saving. The Paradex fee schedule also lists separate Pro charges and a delisting settlement fee, so zero normal trading commission should never be rewritten as zero charges under every circumstance.
Lighter: zero commission on Standard, a different bargain on Premium
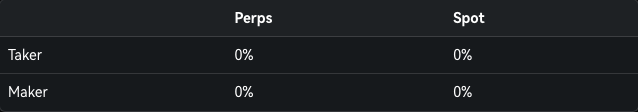
Lighter gives a cost-conscious trader another concrete way to avoid normal maker and taker fees. Standard is the default account category. The current account table shows a 300 ms taker delay, while Premium exchanges a paid tariff for different timing. Plus is a third category with its own fee and rate limits. There is no good reason to describe the entire exchange using the Standard price and the Premium execution conditions at the same time.
For a manual trader, Standard is the relevant comparison with Paradex Retail. For a program that sends many updates, the paid tiers may be the appropriate comparison. At the published no-staking Premium rates, a 10,000-dollar market entry and market exit incur 5.60 dollars in commission. That is lower than the 10 dollars calculated from the Binance and OKX regular USDT rates, but it is not a complete execution comparison. The price received can reverse a difference of a few dollars.
The practical advantage is the ability to choose the account characteristics you actually need. The limitation is that switching category changes the calculation. If you selected Premium for order management, do not continue budgeting with Standard's zero.
Deribit: the lowest confirmed regular centralized taker rate in this set
Deribit Standard publishes 0.015% maker and 0.035% taker for futures and perpetuals. Two immediate fills of 10,000 each therefore cost 7 dollars, compared with 10 at the Binance and OKX regular USDT rates and 11 at Bybit VIP 0. That makes Deribit a serious first comparison for an eligible trader whose intended contract is listed, rather than an exchange to overlook because it is more specialized.
The fee help page still uses the word upcoming, but the separate official change announcement supplies the effective date: 1 August 2026. Reading those together resolves the timing question. The published Standard row can be compared; account discounts and special order treatment still need their own scope.
The saving does not erase product differences. A BTC-settled inverse contract cannot simply replace a desired USDT payout, and cross-collateral liabilities can incur additional charges. Deribit wins this particular centralized base-commission comparison, while the better completed trade still depends on the contract and its executable price.

Hyperliquid: a useful paid benchmark for on-chain order-book trading
Hyperliquid's base validator-operated perpetual schedule lists 0.015% maker and 0.045% taker before volume and staking adjustments. This gives a 6-dollar maker-entry/market-exit commission or a 9-dollar market/market commission on the reference position. It is a worthwhile benchmark for someone whose funds are already in its trading balance: a move to a nominally free platform must save enough to justify moving collateral and obtaining a comparable fill.
Use the actual market category. The Hyperliquid fee documentation distinguishes the base schedule from deployer-built markets and other adjustments. A low tariff advertised for a different type of contract does not automatically transfer to BTC. Similarly, a staking discount is an account qualification, not an entry-level rate available without additional holdings.
Hyperliquid is not our cheapest commission recommendation, but it can still produce a cheaper completed trade than a zero-commission competitor if its price is sufficiently better. On a 10,000-dollar round trip, a 9-dollar fee disadvantage needs a total execution advantage greater than 0.09% to be reversed. That threshold is measurable. Calling one platform more liquid without checking the relevant contract would not answer the question.

OKX: a straightforward USDT futures cost reference
OKX's regular rate in its futures calculation guide is 0.02% maker and 0.05% taker. For an eligible account using the specified product, that is 2 dollars to enter passively and 5 dollars to leave immediately on a 10,000 USDT position. It ties Binance's corresponding base USDT commission in this study. A claim that one is cheaper needs a fee tier, execution difference or holding-cost result, not a different label on an identical calculation.
The advantage of this reference is that it can be compared directly with the BTC-USDT funding history collected below. The quoted commission and the recorded funding belong to an identifiable futures product. It avoids the common mistake of using a spot fee because that figure is more prominent on a general exchange review.
For a trader keeping collateral in USDT and opening occasional BTC positions, OKX is a useful starting point. Its disadvantage against the free manual products is the commission on both sides. Its advantage cannot be assumed from that rate alone: a better fit with the account you already use, a competitive executable price and less collateral movement may outweigh a small difference. The detailed OKX dossier covers the platform beyond its fee schedule.

Binance: compare the USDT and USDC schedules separately
Binance's ordinary USDⓈ-M USDT example also uses 0.02% maker and 0.05% taker. That puts it level with OKX on the fee-only reference trade. Its fee explanation describes a BNB payment discount, but the baseline here assumes no BNB holding. A reader should be able to reproduce the entry-level comparison without acquiring an extra token first.
The USDC column can have different promotional terms from the USDT column. That creates a legitimate opportunity, but only if the target contract is available, the promotion applies to the account and conversion does not consume the saving. A USDC price should not be presented as the cost of a USDT contract simply because both track Bitcoin.
Binance is competitive when you already operate within its futures account and can use the contract that matches your balance. Its position in the collected BTC funding comparison changed between the one-day and seven-day windows. Compare the window closest to your planned holding period alongside the two trading commissions.

Bybit: a small commission difference can be overtaken by funding
Bybit's regular futures row is 0.02% maker and 0.055% taker. A passive entry and market exit cost 7.50 dollars on the reference size, while two immediate fills cost 11 dollars. That is 1 dollar more than the two-taker Binance or OKX example. It is a real difference, but small enough that a different fill or funding window can change the completed comparison.
Our seven-day BTC funding sample illustrates that point: Bybit's positive funding sum was lower than the other two collected exchanges. For a long held through that exact window, the saving exceeded the additional market-order commission. For a short, receiving less positive funding moves the comparison in the opposite direction. Neither result supports calling Bybit permanently cheaper or permanently more expensive.
For the sampled BTC long, the seven-day funding saving paid for Bybit’s extra regular taker commission; the three-day saving did not. That gives the holding period a measurable role in the decision. A trader using the same entry and exit profile should compare the funding difference with the one-USDT commission gap per 10,000 exposure, rather than require Bybit to have the lowest advertised percentage before considering it.

Kraken: the futures fee is not the full multi-collateral bill
Kraken's entry-level derivatives commission also starts at 0.02% maker and 0.05% taker. Its derivatives fee document separates that tariff from conversion charges and charges associated with non-USD-backed losses. Someone using the Multi-M product should therefore compare more than the two percentages in the trading-fee column.
The practical question is what happens when a loss or fee must be settled in a currency you do not hold. An account with sufficient supported dollar collateral is a different cost case from an account funded only with a volatile coin. The fee document describes those conditions; they should not be added as an arbitrary extra charge to every Kraken trade.
Kraken remains a relevant choice when its derivatives product is available to your account and its collateral arrangement fits how you trade. We do not put its spot-margin opening and rollover fees into this perpetual comparison. Those belong to a different product, even though both use the Kraken name. This distinction prevents an apparently expensive or cheap result from being created by comparing the wrong account.
What does opening and closing the same futures trade cost?
A round-trip estimate needs two fills. On a constant 10,000 position, multiplying the maker rate by 10,000 once does not tell you what you pay to get back out. The calculator below separates the entry and exit choices. It uses the scoped schedules above, excludes VIP and token discounts, and leaves funding and execution as explicit additions. Its result is a commission estimate, not a promised total bill.
Calculate your entry and exit commission
Qualifying Retail perpetual orders. Entry 0% + exit 0% on their respective filled values. Funding, price differences and transfers are not included.
Immediate entry and immediate exit
Two taker fills produce 0 dollars in normal trading commission for the free manual profiles, 9 dollars for Hyperliquid's base profile, 10 dollars for Binance or OKX and 11 dollars for Bybit. All of those figures assume unchanged position value between entry and exit. If you close a profitable long for 10,500 rather than 10,000, the second percentage applies to 10,500. The slightly higher closing commission is caused by the value traded, not a mysterious profit tax.
Suppose the Binance and OKX trades each incur 10 dollars in commission. If one delivers an entry and exit that together are 4 dollars better, it wins the execution-and-commission comparison by 4 dollars. Ranking those two by their identical fee percentage adds no information. The comparison only becomes useful when it states what actually breaks the tie.
Passive entry followed by a market exit
Using a maker entry and taker exit changes the reference commissions to 6 dollars for Hyperliquid, 7 dollars for Binance or OKX and 7.50 dollars for Bybit. The maker saving is earned only on the quantity that really rests and fills. If half the entry fills passively and the remainder is taken immediately, calculate the two portions separately; do not assign the entire position the cheaper rate.
There is also a cost that no fee table can settle: the price may move away while you wait. Assume, purely as an example, that waiting saves 3 dollars but you eventually enter 12 dollars worse. The completed purchase is 9 dollars more expensive. That does not make passive orders a bad choice; it means a maker-only calculation should not be advertised as the inevitable price of a trade that needs immediate execution.
Frequent trading changes the importance of a small difference
For twenty unchanged 10,000 USDT round trips, two-taker commission is 200 dollars at 0.05% per side and 220 dollars at 0.055%. The 20-dollar gap is the fee advantage across 400,000 USDT of total filled value. It is not a saving on a 10,000-dollar deposit. Reusing the same collateral creates repeated trading volume and repeated commissions.
Leverage makes the debit more noticeable against margin, but the rate still applies to traded value. A 10-dollar commission is 1% of 1,000 dollars posted for a 10,000 position. It is 10% of 100 dollars posted for that same position. The fee has not increased; the collateral denominator has shrunk. This is why moving to a higher multiplier is not a fee-saving strategy.
| Profile | Market / market | Maker / market | Maker / maker |
|---|---|---|---|
| Paradex Retail | $0.00 | $0.00 | $0.00 |
| Lighter Standard | $0.00 | $0.00 | $0.00 |
| Deribit Standard | $7.00 | $5.00 | $3.00 |
| Hyperliquid | $9.00 | $6.00 | $3.00 |
| OKX | $10.00 | $7.00 | $4.00 |
| Binance | $10.00 | $7.00 | $4.00 |
| Bybit | $11.00 | $7.50 | $4.00 |
| Kraken | $10.00 | $7.00 | $4.00 |
When zero trading fees do not mean the cheapest trade
The useful comparison is the price for the order you intend to execute. A small displayed spread at the top of the book does not establish the average price for an order that consumes several levels. Conversely, a pool-based exchange should be compared using its quoted trade output and charges, not marked as having no liquidity because it does not publish a conventional order book.
The fee is zero. The trade still costs more.
Hypothetical $10,000 position at entry and exit.
Entry fills $8 worse; exit fills $7 worse.
$10 in fees; no worse fills against the same reference.
If your average entry and exit prices already measure the difference from the midpoint, they include the spread crossed and any additional movement through the book. Adding a separate spread estimate again would double-count part of the cost. An honest comparison either reports one combined execution difference or carefully decomposes it. It should not make the paid venue look worse by counting the same price disadvantage twice.
| Paid alternative | Two-taker commission | Break-even total execution difference |
|---|---|---|
| Hyperliquid base | $9 on $10,000 each way | 0.09% of one reference position |
| OKX / Binance regular | $10 on $10,000 each way | 0.10% |
| Bybit VIP 0 | $11 on $10,000 each way | 0.11% |
The wallet and collateral transfer can change a small-account result
A first trade on a new chain can require a withdrawal from an exchange, a bridge or a conversion into supported collateral. These are costs of reaching the venue. They should be shown separately from recurring order commissions because they are not necessarily paid on every trade. If a move costs 6 dollars and saves 1 dollar per completed trade, it needs six comparable trades just to recover that initial cost, before considering price differences.
That distinction is especially relevant for a small balance. Someone who already has usable collateral in a protocol is not in the same position as someone starting with money in a bank account. A ranking can fairly prefer a zero-commission platform for one reader and an existing centralized account for the other. The conclusion follows from their starting balances, not from changing the definition of cheap midway through the article.
For GMX or Jupiter, include the particular market's opening and closing quote, any borrowing or carry charge, and transaction execution costs. Their fee rules do not reduce to a universal maker/taker pair. We therefore keep them outside the fixed order-book tariff table rather than inventing an equivalent rate. A native quote can still beat an order-book route; it must be compared on the same exposure and holding period.
Overnight futures costs: what the collected funding history shows
We collected settled BTC perpetual funding observations from Binance, Bybit and OKX on 4 October 2026. The shared sample ends at 16:00 UTC that day. It contains matching eight-hour timestamps, allowing one-day, three-day and seven-day comparisons. Binance timestamps with a few extra milliseconds were normalized to their settlement second. All calculations use a constant 10,000 USDT exposure, so they isolate funding rather than reconstruct a changing-position trading account.
Seven-day BTC funding cost
10,000 USDT constant long exposure · ending 4 Oct 2026, 16:00 UTC
View calculations and download the observations
| Product | Funding | Long + fees | Short + fees |
|---|---|---|---|
| binance | 8.0784 | 18.0784 | 1.9216 |
| bybit | 5.8854 | 16.8854 | 5.1146 |
| okx | 8.0302 | 18.0302 | 1.9698 |
Sum of 21 settled rates × 10,000. No compounding. USDT treated at USD parity. Short reverses the funding sign.
Download dated observationsOver the final 24 hours, a long's calculated funding cost was about 0.59 USDT on Binance, 0.85 on Bybit and 0.90 on OKX. Over seven days, it was about 8.08, 5.89 and 8.03 respectively. The lowest funding result changed with the window. An exchange that looks cheapest in a screenshot of the current rate can therefore lose over the period you actually plan to hold.
Combining the seven-day funding sum with the regular market-entry and market-exit commissions gives approximately 18.08 USDT for Binance, 16.89 for Bybit and 18.03 for OKX. Those totals exclude execution differences, conversion and any account-specific discounts. Within that defined model, Bybit beats the other two for a long despite its higher taker fee.
The short side produces a different conclusion
The net funding sums in the seven-day sample are positive, so a short receives rather than pays them. Subtracting that receipt from the same commission assumptions leaves about 1.92 USDT for Binance, 5.11 for Bybit and 1.97 for OKX. Binance and OKX are nearly tied on this partial-cost basis. The difference is too small to treat as a durable advantage once real execution is included.
This does not mean a short earns a reliable yield. The position still gains or loses as the crypto price changes, funding can reverse, and the recorded window is historical. The point is narrower: a low funding rate benefits the payer while reducing the receiver's credit. A ranking that labels lower funding as universally better is applying the wrong logic to half its readers.
What this sample can and cannot establish
The raw observations are available with the chart. They are public funding records, not our executed trades. We did not continuously rebalance a live position to maintain exactly 10,000 USDT. The fixed exposure is a comparison convention. A real BTC quantity held unchanged would acquire a different notional value as Bitcoin moved, changing each settlement amount.
We also did not substitute zero for venues lacking an equivalent collected history. Paradex and Lighter's free commission does not imply zero funding. To compare one of them with the seven-day results, obtain its settled payments for the same interval and direction. That gap is a reason to limit the conclusion to these three products, not a reason to pretend the other products performed badly.
Manual trading and API futures fees are not always the same
An API order is simply an order sent by software, but exchanges can price that channel differently. MEXC explicitly separates its API tariff from web and app offers. Paradex classifies orders by submission method and interactive status. Lighter's account categories exchange different fees and timing conditions. These differences can overwhelm the commission savings advertised on a homepage.
| Profile | Maker / taker | What changes |
|---|---|---|
| Paradex Pro | 0.003% / 0.045% | Pro 0; no DIME or FastFills discount |
| Lighter Premium | 0.004% / 0.028% | No LIT staked; Premium conditions |
| Lighter Plus | 0.005% / 0.005% | Plus account, 0.5 bps each side |
| MEXC API | Conflict: 0.06% / 0.08% vs 0.04% / 0.06% | Adjustment table and example disagree; excluded from confirmed price ordering. |
MEXC: the documented conflict remains material
The June API update says the post-adjustment maker/taker rates are 0.06% and 0.08%. The worked example beneath it still uses 0.04% and 0.06%. Both are separate from manual promotions. On a 10,000-dollar taker round trip, those taker alternatives imply 16 or 12 dollars before funding. The disagreement is large enough that choosing one silently would change the result.
We exclude MEXC from the confirmed API price ordering until the applicable current rate is resolved by an authoritative account-specific schedule or a corrected notice. For manual trading, it remains a candidate for eligible promotions. This is more useful than either dismissing the exchange entirely or advertising a promotional manual rate to a reader who intends to automate orders.
Paradex: interactive API is an exception worth understanding
The simple claim that every API order pays Pro fees is also incomplete. Paradex documents interactive API tokens that submit Retail orders, subject to Retail limits. Exceeding those limits changes the behavior. A low-frequency interactive tool and a high-throughput automated strategy therefore do not necessarily fall into the same price category, even though both use an API.
For standard Pro flow, the published base maker/taker pair is 0.003% and 0.045%. That implies 0.30 dollars for a 10,000-dollar passive fill and 4.50 dollars for an immediate one before discounts. A maker entry and taker exit total 4.80 dollars. The zero Retail calculation cannot be applied to that Pro trade simply because both originate from the same wallet.
The decision for an automated trader should be made on its actual order pattern: the permitted channel, the account category, how often orders are cancelled and what fees appear on fills. The fastest published API allowance is not itself a price advantage, and the cheapest nominal tariff may not support the required interaction pattern.
VIP tiers, token discounts and referral offers
A discount is useful only when the value saved justifies the condition required to obtain it. Suppose holding an extra token reduces your expected monthly futures commission by 12 dollars. That is the relevant fee benefit to compare with the capital committed and the token's price movement. A headline reduction of 10% sounds larger than 12 dollars, but they can describe the same offer.
Volume tiers should follow trading you intended to do anyway. Generating extra trades merely to reach a lower tier can cost more than the future saving. Compare the fees on your expected activity before and after qualification, and account for the fact that many tiers are based on a rolling window. Reaching a tier once does not necessarily lock it in forever.
Referral benefits also need to be distinguished from the standard schedule. Our buttons use the registered partner destinations, but the calculations do not assume an undocumented permanent discount. Signup credits, fee vouchers, points and withdrawable cash are different benefits. A voucher that expires before your next trade cannot be treated as cash reducing every future order.
Finally, an advertised maker rebate is a credit attached to eligible executed volume. It is not interest on idle collateral, and a resting order that never fills produces no trading rebate. Comparing negative maker rates without considering the taker exit can make an account appear to pay you for a complete trade when only one side earns a credit.
Reconciling the fee estimate with a completed order
A filled entry can contain both maker and taker portions. Suppose 6,000 USDT rests at a 0.02% maker rate and the remaining 4,000 executes at 0.05% taker. Entry commission is 1.20 plus 2.00, or 3.20 USDT. An unchanged-value 10,000 taker close adds 5.00, making 8.20 in total. Applying the maker rate to the entire entry would understate that bill by 1.20 USDT.
Use filled value rather than the original requested amount when an order only partly executes. A 10,000 request that fills 4,000 creates commission on the 4,000 fill, not the unfilled 6,000. The fee schedule still applies; the quantity to which it applies has changed. The order history’s individual fills therefore explain a result that a single headline percentage cannot.
Finally, separate a reserved closing allowance from an actual closing charge. The former can reduce available margin before the trade finishes; it should not be deducted a second time after counting the executed closing fee. Reconcile commissions from fills, funding from settled events and transfers from the transfer record. This produces a bill you can compare with the estimate without counting the same deduction twice.
Low-fee futures questions
Is a zero-maker-fee account cheap if I always exit at market?
Only the entry is free in that case. At a 0.05% taker rate, closing 10,000 USDT costs 5 USDT even if the entry paid nothing. A stop that executes as a market order also uses the applicable taker rate. Compare your likely exit behavior with the advertised maker benefit; a zero-maker banner alone does not describe your round trip.
Why does a limit order sometimes pay the taker fee?
Because the limit is your worst acceptable price, not an instruction to wait. If it matches an existing offer immediately, it takes liquidity. A post-only instruction can prevent that immediate match, but may reject or cancel the order instead of filling it. Check the role recorded against each fill; part of an order can execute differently from the remainder.
Does increasing leverage make the exchange charge a higher fee rate?
Usually the published commission rate does not change merely because you move the leverage slider. What matters is the value you trade. Keeping a 10,000 USDT position while reducing margin leaves the same fee calculation; using the same margin to open a larger position increases it. Those are different actions, and confusing them makes fees appear unrelated to the schedule.
Can I avoid funding by closing before the displayed payment time?
On products that settle only at discrete times, not holding a position at the relevant settlement can avoid that payment, subject to the exchange's timing rules. This does not apply universally: some products accrue funding continuously. Closing and reopening also generates commissions and execution costs, so compare the payment avoided with the cost of those extra fills before treating it as a saving.
Does a referral discount reduce my funding payments?
Do not assume so. A trading-commission discount normally targets eligible maker or taker charges, while funding follows the contract's separate mechanism. Points or vouchers may have still different conditions. None of the calculations on this page subtracts an unverified referral benefit from funding. The relevant offer needs to identify the exact fee it reduces and any limit on how long that reduction lasts.
Are mobile app and automated futures orders charged equally?
Not on every venue. The important distinction can be the trading channel or the classification of the order rather than the device. MEXC explicitly separates API pricing; Paradex distinguishes normal Pro API flow from Retail and qualifying interactive flow. A person tapping a phone and a bot sending orders from a laptop should not automatically use the same fee estimate.
How do I compare a pool-based perpetual with these order-book rates?
Start with the pool's quote for the same position and intended direction. Add its stated opening, closing, ongoing and transaction costs, then compare the net result with an executable order-book quote. A maker/taker label is not necessary for a valid comparison. What matters is avoiding omitted charges and using the same exposure, holding period and collateral assumptions.
Should I buy an exchange token just to qualify for lower fees?
Calculate the expected dollar saving first. If the discount saves 8 dollars per month but requires a much larger token holding, that token becomes a separate position whose price changes can outweigh the fee benefit. A discount can make sense for substantial organic trading volume; it is not automatically attractive because the percentage printed in the VIP table is large.
Can these funding results predict the cheapest exchange next week?
No. The collected records establish what the specified BTC products charged over the reported interval. They do not predict demand for long or short positions next week. Use the historical result to understand how commission and funding interact, then review a fresh, comparable window for a new decision. An annualized rate extrapolated from one settlement would give a false sense of precision.
Sources and research
Official documentation reviewed on 4 October 2026. Account-specific screens can apply different terms. Funding has its own dated collection window.
- Paradex — trading fees
- Paradex — Retail and Pro order classification
- Lighter — Standard, Plus and Premium accounts
- Hyperliquid — fee schedules
- Binance — futures fee calculation
- Bybit — regular futures and VIP schedule
- OKX — futures fee calculation
- Kraken — derivatives and collateral charges
- MEXC — June API fee change (table/example conflict)
- MEXC — conditional new-user futures rates
- Deribit — fee tiers and order attributes
- Gate — product-specific account fee overview
- GMX — position, impact and ongoing fees
- Jupiter — perpetual fee models
- Bybit — BTCUSDT settled funding records
- OKX — BTC-USDT-SWAP settled funding records
- Binance — BTCUSDT settled funding records
- Deribit — fee schedule effective 1 August 2026